Most people already know they should save more. The hard part is making it happen when rent, groceries and a dozen small bills seem to take every dollar first.
Below are 13 ways to save money, in the order they usually work best, plus plans for saving fast, saving on a small income and saving at any age.
How to save money: start in the right order
If you’re figuring out how to save money from scratch, the order matters more than any single trick.
A common order is simple: build a small cushion, grab any free employer money, clear costly debt and then save for bigger goals. Plans such as the Dave Ramsey Baby Steps follow a similar path, though they differ on details like when to invest for retirement.
You don’t have to follow any plan perfectly. What matters is knowing which job your next dollar is doing, so each tip below has a clear place in line.
Set up a saving system that runs itself
Willpower runs low at the end of a long week. A system that moves money before you see it does the work for you, and it takes about an afternoon to set up.
1. Pay yourself first
Paying yourself first means treating savings like a bill you pay on payday, before groceries, takeout or anything else. Instead of saving what’s left at the end of the month, which is often nothing, you save first and live on the rest.
Pick an amount that feels a little tight but doable, such as 5% of your take-home pay. You can raise it later, and a small amount you never skip beats a big one you give up on by March.
2. Automate the transfer on payday
Next, set up an automatic transfer from checking to savings for the day your pay lands. Many employers can also split your direct deposit, so part of each paycheck goes straight to savings.
Automation works because it removes the decision. If you’re paid every other week, saving money bi-weekly lines transfers up with your pay and uses the two “extra” paychecks each year.
3. Keep savings in a separate account
Money sitting in checking tends to get spent, even with good intentions. A separate savings account, ideally at a different bank, adds a small barrier that makes impulse transfers less tempting.
That barrier is also how you save money without spending it. Look for a high-yield savings account at a bank backed by the FDIC, which insures deposits up to at least $250,000 at each insured bank.
4. Give your savings a specific goal
“Save more” is easy to ignore, but “$4,000 for a car fund by December” gives you a number and a deadline. Divide the target by the months you have, and you know what each transfer needs to be.
A clear goal also makes it easier to skip small purchases, because you can see what they’re competing with. Bigger targets like saving for a house or moving out on your own work best as monthly milestones.
Build your safety net first
With the system running, your first savings should protect you from the next surprise. Without that cushion, one flat tire can wipe out months of progress or land on a credit card.
5. Start a starter emergency fund
An emergency fund is money set aside only for real surprises, like a job loss, a medical bill or a broken water heater. Many plans start with a small first target you can reach in a few months, then build toward several months of essential costs.
That first target matters because an early win keeps you going. If you’re following Ramsey’s approach, the emergency fund guide explains how his starter and full funds differ.
6. Use sinking funds for costs you can see coming
Car tags, holiday gifts and yearly insurance bills aren’t emergencies, just costs that don’t come every month. A sinking fund saves for each one a little at a time, so it never lands as a shock.
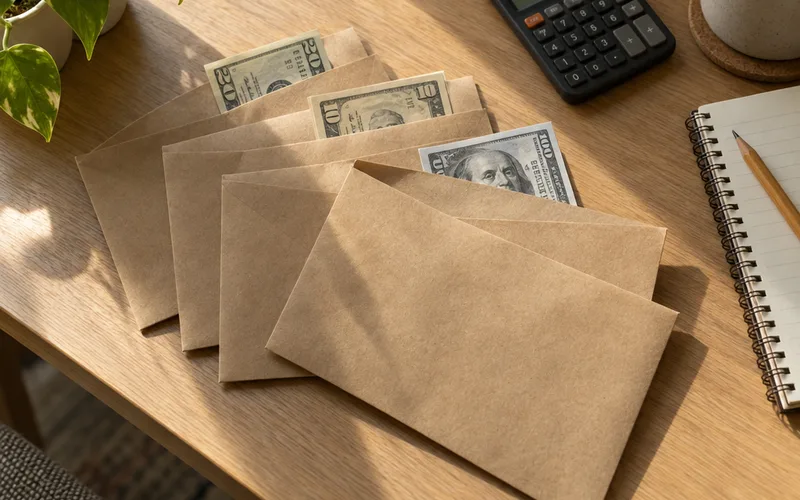
For example, a $720 yearly car insurance bill becomes $60 a month set aside in its own savings bucket. Start with the two or three costs that surprise you most, and setting up sinking funds gets easier from there.
7. Capture the match, then pay off high-interest debt
If your employer matches 401(k) savings, put in at least enough to get the full match, because that’s free money. Next, go after high-interest debt, because credit card interest usually grows far faster than a savings account can pay you.
Once those balances are gone, the money you spent on interest can go to savings. A focused plan for becoming debt free faster shows which balance to target first.
Free up more money to save
Automation decides where money goes, but you still need money to send, so these tips make room without cutting everything at once.
8. Find your numbers with a simple budget
You can’t save what you can’t see, so start by tracking a month of spending. Then check it against the 50/30/20 rule: 50% of take-home pay for needs, 30% for wants and 20% for savings and debt.
Your split doesn’t have to match, especially in a high-cost city, and spending on wants you truly value is part of the plan. The Budgeting guides show how to build a full plan around the savings rate that works for you.
9. Cut one big recurring bill
Cutting one recurring bill keeps paying you back every month, which usually beats skipping a coffee. Insurance, phone plans, internet and unused subscriptions are good places to look.
Get a competing quote before your next renewal, then ask your current provider to match it. Move the monthly difference straight into savings, and the Bills guides cover many more ways to shrink those payments.
10. Spend less on food without eating worse
Food is one of the biggest costs you can change week to week. Planning a week of meals and shopping from a list cuts both impulse buys and food waste.
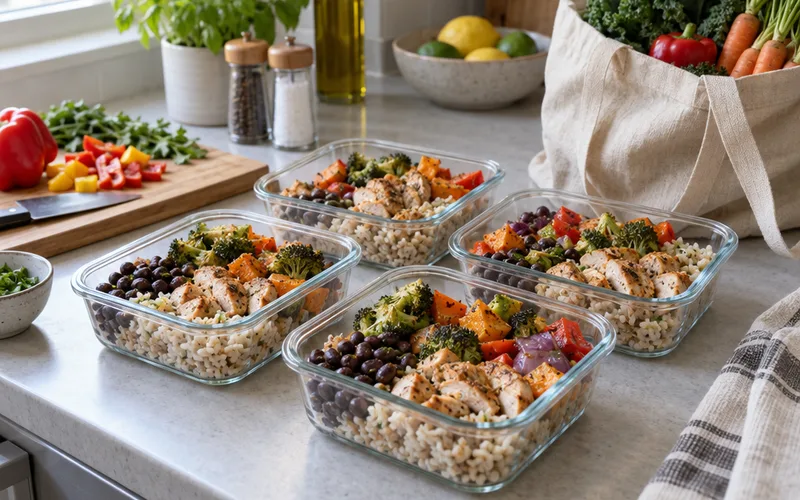
Transfer what you didn’t spend so the saving shows up in your account. The Groceries guides have meal plans and shopping tips for going further.
11. Save raises, refunds and windfalls
A raise, a tax refund or a cash gift is the easiest money to save, because you were already living without it. Before it arrives, decide how much goes to savings, such as half of every raise and most of every refund.
This also keeps your spending from rising every time your pay does. For everyday habits that free up more cash, the Frugal Living tips focus on changes that stick.
Make the habit stick
Most savings plans fade quietly in the second or third month, so these last two tips are about staying with it.
12. Turn saving into a challenge
A challenge gives you a clear rule and a finish line. The savings challenges range from short sprints to full-year plans, so you can pick one that fits your pay.
The classic 52-week money saving challenge saves $1 in week one, $2 in week two and so on, ending at $1,378. For a bigger target, saving $10,000 in a year works out to about $833 a month.
13. Track your progress where you’ll see it
Watching a balance grow is a strong motivator. A chart on the fridge, a note on your phone or a budgeting app keeps the goal in front of you.
Check in once a month, not every day. If you miss a target, lower the amount instead of quitting, since a small plan you keep beats a perfect one you drop.
How to save $1,000 fast
Saving $1,000 quickly is mostly simple math plus a short burst of effort. Over 90 days, $1,000 works out to about $78 a week, or roughly $11 a day.
To hit that number, stack a few moves: pause a subscription or two, sell things you no longer use, try a no-spend week and pick up an extra shift if you can.
Send every dollar from those changes to savings the same day. In 30 days, you’d need about $250 a week, which usually means earning extra rather than only cutting costs.
Saving money on a low income
When money is tight, even $5 or $10 a week builds the habit and slowly adds up. Start with that small automatic transfer, then add one-time money like tax refunds when it comes in.
America Saves, a campaign run by the nonprofit Consumer Federation of America, encourages people to set small, specific goals. The guide to saving on a low income adds help programs and low-cost ways to cut fixed bills.
Saving at every stage of life
Teens can start with a first job and a simple account, and saving as a teenager shows how to split each paycheck.
Students juggle tight budgets and uneven income, so these money-saving ideas for students start with books, food and getting around. If you’re aiming much higher, the FIRE movement explains how some people save a large share of income to retire early.
If you’d rather learn from a book, a classic book on saving can help you think through the habits behind the numbers. Whatever stage you’re in, the next step is the same: pick one tip from this list and set it up this week.
Frequently Asked Questions
What is the 50/30/20 rule?
The 50/30/20 rule splits your take-home pay into 50% for needs, 30% for wants and 20% for savings and debt. It’s a starting point, so adjust the split if your rent is high.
How can I save $1,000 fast?
Aim for about $78 a week over 90 days. Pause subscriptions, sell unused items and add extra income, then move each dollar to savings the same day.
How do I save money without spending it?
Keep savings in a separate account, ideally at a different bank, and move money there automatically on payday. The extra step to move it back makes impulse spending less likely.
What should I do with my savings?
Start with an emergency fund in an insured savings account, then use extra savings to pay off high-interest debt. After that, save toward goals like a house, retirement or a big purchase.
How do I save money for the future?
Automate a set share of every paycheck, get any employer retirement match and raise your savings rate each time your pay grows.